A risk team can add policies, systems, and reporting tools for years without necessarily building a more mature way of working with the information those tools hold. The clearest evidence of insurance program maturity appears in recurring work. A mature operating model allows the team to compare renewals without rebuilding the analysis, answer executive premium questions consistently, and understand program structure without searching through broker materials and prior-year files before anyone can respond.
A mature insurance program gives risk leaders reliable policy information, comparable history, program-level visibility, and governance practices that support recurring decisions. Organizational scale and technology inventory may increase complexity, but decision capability reveals whether the operating model has matured with it. Insurance program maturity is measured by how reliably the risk team can answer recurring decision questions with governed, comparable, program-level information, not by company size, premium spend, or the amount of technology it owns.
Insurance Program Maturity Shows Up in Recurring Decisions
A mature program answers recurring questions consistently across renewal, reporting, governance, and program review. The speed and confidence of those answers reveal more about the operating model than the size of the insurance function ever could.
What changed in this policy since last year? Where did premium move, and why? Which carriers participate across the program, and has that changed? How do current limits and retentions compare with prior periods? Which entities does a given coverage actually apply to? How has the program's structure evolved over several policy years? These questions recur across renewal, executive reporting, governance review, and program analysis, often for the same underlying insurance information, asked by different people at different times.
Having every source document available does not guarantee quick answers. A team can have every policy on file and still spend hours locating the relevant terms, reconciling values across spreadsheets, or tracking down whoever remembers how the program looked two renewals ago. That reconstruction work is decision friction. An inventory of systems or a count of policies rarely reveals it until someone actually needs an answer.
Decision Capability Is a Better Measure Than Organizational Scale
Premium spend, policy count, headcount, and technology inventory describe scale. They do not establish whether insurance information is reliable, comparable, visible, or governed well enough to support decisions.
A large organization running several systems can still reconcile renewal data by hand every cycle, with each system holding a partial answer and nobody quite sure which version is current. A smaller organization with a genuinely complex program, multiple entities, layered coverage, several carriers, can have clear ownership of its insurance information, a repeatable way to compare policy years, and executive reporting leadership actually trusts. The second organization is more mature, even though it is smaller and likely spends less on insurance technology.
Scale and complexity are real. They shape how much a program has to manage. They do not, on their own, say anything about whether the organization manages it well.
A RMIS, a policy management platform, or another insurance technology contributes to a mature operating model when it supports reliable, comparable, governed decisions. The value comes from how the technology supports the team's work, regardless of the specific systems in place.
Five Dimensions Define Insurance Program Maturity
Maturity is multidimensional. Strength in one area cannot compensate indefinitely for weaknesses that interrupt recurring decisions elsewhere.
Policy-Information Reliability
This dimension asks whether policy, coverage, premium, limit, retention, carrier, entity, and date information is consistently available, validated, and traceable to source documents. A team that can answer a routine coverage question without reopening the underlying policy has a reliability advantage a larger, less organized program often lacks. ACORD's data standards provide common definitions for exchanging insurance information across systems and trading partners. Consistent definitions help make information reliable enough to compare and reuse.
Historical Comparability
This dimension asks whether the team can compare policies and program structures across policy years without recreating the history for each renewal or leadership question. Keeping prior policies preserves the documents. Maturity requires usable comparisons, as explained in more depth in comparing insurance programs across policy years.
Program-Level Visibility
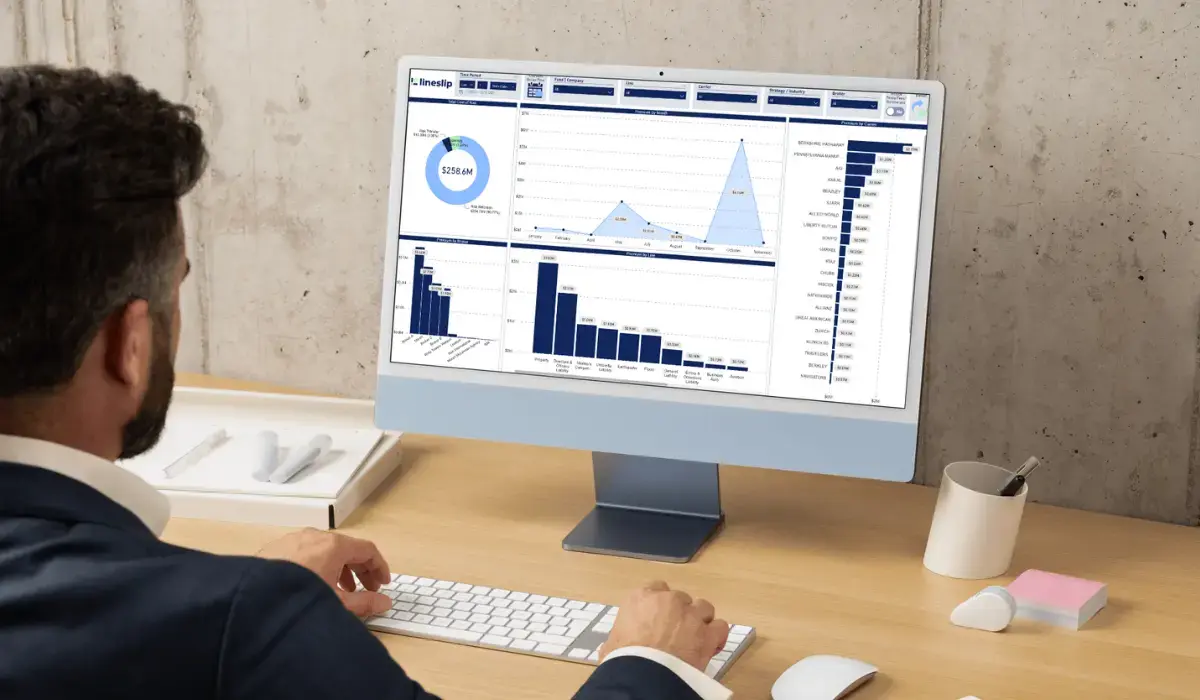
This dimension asks whether relationships among policies, entities, carriers, layers, premiums, limits, retentions, and attachment points are visible across the program, rather than only within separate records. A layered program in particular tends to expose this gap, since no single policy shows how a carrier participates elsewhere in the tower. LineSlip's Program Schematic is one example of what program-level visibility can look like in practice, surfacing carrier, layer, and attachment relationships together rather than requiring them to be reconstructed policy by policy.
Governance Practices
This dimension asks whether ownership, validation, definitions, source traceability, update practices, and reporting responsibilities remain clear as the program changes, the same practices covered in more depth in a closer look at insurance data governance for enterprise risk teams. When these practices depend entirely on one person's memory, continuity can break during a transition, an acquisition, or a leadership change.
Recurring Decision Readiness
This dimension asks whether renewal, executive reporting, governance review, policy comparison, and program analysis can begin with accessible information instead of repeated reconstruction and reconciliation. The other four dimensions become visible here because recurring decisions expose whether the program can produce dependable answers. This practical test is explored further in insurance reporting that supports decisions.
Five-Dimension Maturity Assessment
|
Dimension |
Evidence of Lower Maturity |
Evidence of Greater Maturity |
Decision Impact |
|
Policy-information reliability |
Values are reconstructed from source documents each time they're needed |
Validated fields are consistently available and traceable to source |
Faster, more confident answers to routine coverage questions |
|
Historical comparability |
Prior policy years require manual reassembly for each comparison |
Policy-year comparisons can be built without recreating history |
Renewal and governance questions start from context instead of scratch |
|
Program-level visibility |
Carrier and layer relationships are pieced together policy by policy |
Program relationships are visible together across the tower |
Concentration, structure, and exposure questions get answered directly |
|
Governance practices |
Ownership and update responsibility depend on individual memory |
Ownership, validation, and update practices are clearly defined |
Continuity survives staff and broker transitions |
|
Recurring decision readiness |
Each new question restarts the reconstruction process |
Renewal, reporting, and review begin from accessible information |
Decisions move faster and with more confidence |
A Three-Stage Model Makes Maturity Observable
Different dimensions may sit at different stages within the same program at the same time. The goal is to identify the operating constraint that most affects current decision capability instead of producing a single score.
Maturity models are a familiar idea in risk management more broadly. RIMS' Risk Maturity Model, for instance, uses a similar approach at the enterprise level, establishing a baseline, identifying strengths and weaknesses, and guiding improvement. The model here is narrower by design. It measures the insurance program's information environment specifically, not an organization's broader enterprise risk management maturity.
These stages are diagnostic patterns for recognizing where a program currently stands. They are neither a certification nor a proprietary benchmark, and organizations may move through them in different sequences and on different timelines.
Reconstructive. Information exists but has to be rebuilt for most recurring questions. Decisions wait on manual work, and continuity often depends on specific people remembering how the program is structured.
Repeatable. Information is validated and comparable within recurring workflows, though visibility across the full program or across every dimension may still be uneven.
Decision-capable. Information is reliable, comparable, visible, and governed well enough to support recurring decisions as the program and the team around it change.
Heads of Risk Can Measure Maturity With Evidence
The strongest assessment evidence comes from recurring work: how information is sourced, validated, compared, updated, and used when a decision question arrives.
-
Can the team answer the same policy or program question consistently across renewal, reporting, and governance workflows?
-
Can current values be traced to authoritative policy documents and validated information?
-
Can policy and program changes be compared across years without rebuilding the comparison?
-
Can the team see carrier, layer, premium, limit, retention, and attachment relationships at the program level?
-
Are ownership, definitions, validation, and update responsibilities clear?
-
Which recurring decisions still depend on manual reconstruction or one person's institutional knowledge?
Direct assessment evidence includes renewal workbooks, policy schedules, governance reports, executive summaries, policy-year comparisons, source-validation workflows, program schematics, and repeated ad hoc requests. These materials reveal more than a system inventory or a general impression of how organized the program feels.
Maturity Priorities Should Follow Decision Friction
The next priority should address the maturity weakness that most often slows, fragments, or weakens a recurring decision, whether that involves information reliability, historical comparison, program visibility, governance ownership, or workflow design.
A Head of Risk can rank issues by decision frequency, consequence, manual effort, confidence, and dependency on individual knowledge. A problem that surfaces every renewal and consumes real time deserves more attention than one that shows up once every few years, even if the second one looks more dramatic on paper. Progress comes from resolving a specific constraint. Adding technology to an unclear ownership model or inconsistent definitions tends to relocate the friction instead of removing it.
Insurance Program Maturity Is an Operating Capability
A mature insurance program gives risk leaders a dependable basis for recurring decisions. Technology, process, governance, and professional judgment reinforce that capability together. No single element defines maturity on its own.
The decisions an insurance program needs to support provide the most useful basis for measuring its maturity. Start with one recurring decision that still requires reconstruction, then work through the five dimensions to identify the source of the friction. That constraint is usually a clearer starting point than a broad initiative aimed at everything at once.
A closer look at what LineSlip does and does not do explains how LineSlip can support this work alongside the people, processes, and systems already involved.
Connect with the LineSlip team to assess where your program sits and which constraint to address first.
Frequently Asked Questions
1. What is insurance program maturity?
Insurance program maturity is the repeatable capability to support insurance decisions with reliable, comparable, visible, and governed information, not a fixed score or certification.
2. How do you measure insurance program maturity?
Maturity is measured across five dimensions: policy-information reliability, historical comparability, program-level visibility, governance practices, and recurring decision readiness, evaluated against evidence from actual workflows rather than a universal score.
3. Does company size determine insurance program maturity?
No. Company size affects the complexity and resources involved, but decision capability, whether the team can answer recurring questions consistently, is the more useful measure of maturity.
4. What should an insurance program maturity assessment evaluate?
An assessment should look at policy-information reliability, historical comparison, program relationships, governance ownership, and recurring decision readiness, using evidence from renewal, reporting, and governance work rather than a system inventory.
5. How can technology support insurance program maturity?
Technology can accelerate access to insurance information, support comparison and program-level visibility, and reinforce governed workflows. It does not replace insurance professionals, and owning more technology is not itself a maturity measure.